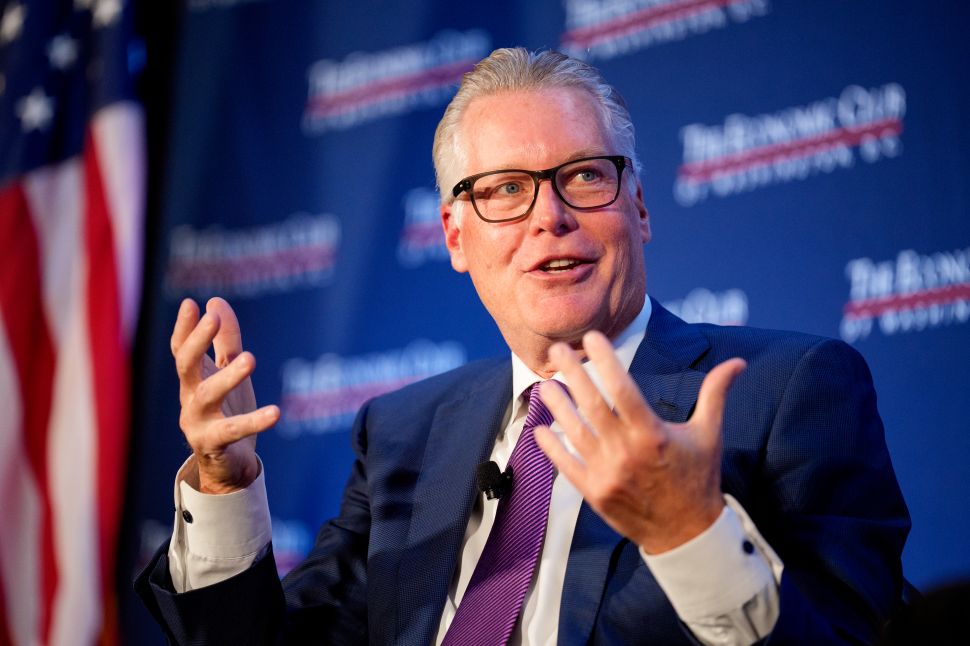
Ed Bastian.” width=”970″ height=”647″ data-caption=’Delta Air Lines CEO Ed Bastian is counting on premium passengers and a lucrative American Express partnership to help the airline weather soaring fuel costs. Delta lowered its 2026 profit forecast on Oct. 9 despite continued revenue growth. <span class=”lazyload media-credit”>Photo by Andrew Harnik/Getty Images</span>’>
Delta Air Lines lowered its 2026 earnings forecast on Oct. 9, saying a $6 billion jump in fuel costs will hold full-year pre-tax profit to roughly $4.5 billion, even as adjusted revenue grew 16 percent during the three months ended Sept. 30, according to a regulatory filing. Despite its lucrative partnership with American Express and growing demand for premium seats, the carrier hasn’t fully offset the surge in fuel expenses.
“There’s no doubt the cost of oil is having a significant impact on airfares,” Julian Kheel, founder and CEO of Points Path, tells Observer. His company operates a browser extension that compares flight prices in dollars and reward points on Google Flights. Fuel generally accounts for a substantial portion of an airline’s operating costs, he explains, but demand remains strong. “That being said, we have yet to see a significant decrease in travel demand, especially as we enter the holidays. So, as long as people are still looking to fly, it’s unlikely that demand or prices are going to drop.”
Delta now expects adjusted earnings of $5.10 to $5.60 per share this year, well below the $6.50 to $7.50 range it set in January and reaffirmed in July. The airline attributed the downgrade to higher jet fuel prices amid the war involving the U.S., Israel and Iran, which has disrupted global energy supplies.
Delta’s adjusted fuel expenses rose 62 percent from a year earlier to $4.14 billion during the three months ended Sept. 30, according to its financial results. Adjusted revenue reached $17.6 billion, although it narrowly missed analysts’ estimates, as did adjusted earnings of $1.72 per share.
CEO Ed Bastian acknowledged the pressure during the company’s earnings call but argued that Delta’s position at the premium end of the market gives it more room to raise fares. “If this continues to go higher for longer—which I think it will—as the premium airline in the industry, we have the best ability to be able to price for that,” he said.
Kheel largely agrees, though he questions whether Delta’s advantage over competitors is quite as secure as Bastian suggests.
“That’s mostly accurate. Delta has certainly been known as a premium airline since before the pandemic, and since the pandemic, people are absolutely looking for premium experiences,” Kheel says. “The part that you might take a little bit of issue with is that United is on Delta’s heels, so whether they are best positioned to absorb those fuel costs and pass prices along to consumers is up for debate.”
How Far Can Delta’s Premium Strategy Go?
The latest results test how much Delta’s emphasis on premium cabins, loyalty programs and credit card revenue can insulate it from soaring fuel prices. The airline has spent years courting higher-income customers, expanding its Delta One lounges and increasing the number of premium seats across its fleet.
Those investments are paying off, at least on the revenue side. Premium ticket revenue grew 18 percent from a year earlier, while payments from American Express rose 15 percent. Delta expects to receive more than $9 billion from its American Express partnership this year.
Premium travel, loyalty programs and other businesses, including cargo and aircraft maintenance, accounted for 61 percent of Delta’s revenue during the period. That’s a considerable cushion, but it hasn’t been enough to prevent a sharp reduction in expected annual profit.
Kheel says the loyalty business has become an enormous asset for major airlines. During the pandemic, some carriers even pledged their frequent-flier programs as collateral to raise financing. These programs can generate revenue beyond ticket sales and give airlines another source of income when operating costs rise.
But that doesn’t mean customers will tolerate higher fares indefinitely.
“At some point people will say that’s too much,” Kheel says.
Delta’s corporate travel business provides another bright spot. Sales to corporate customers grew by double digits across every sector, led by banking, technology and energy, with particularly strong performance in Boston and Los Angeles. Executives are still traveling, and higher corporate demand is helping Delta fill its more expensive seats.
That’s significant for an airline whose results are closely watched as an early indicator of industry performance. Delta is the first major U.S. carrier to report earnings, offering a glimpse into how higher fuel costs, corporate spending and consumer demand are affecting airlines before competitors such as United and American report their numbers.
Delta’s premium-heavy business also makes it a useful gauge of spending among wealthier travelers, who have generally been better positioned to absorb higher ticket prices. But even those passengers have limits.
Higher Fares May Be Here to Stay
Kheel expects fuel costs to remain a substantial headwind for airlines. Carriers can raise fares to cover higher expenses, but only for as long as travelers are willing to pay. That leaves airlines trying to balance their margins against the risk of weakening demand, even among premium customers.
And if oil prices eventually fall, there’s no guarantee airfares will follow. Airlines that successfully raise prices during the current fuel shock may be reluctant to reverse those increases if demand holds up, much as prices for many goods and services remained elevated after the pandemic.
“I think long-term the airlines could end up in a pretty good place where they’re able to pass along and hold these higher prices,” Kheel says. “But in the short term, we’re probably going to see some pain.”