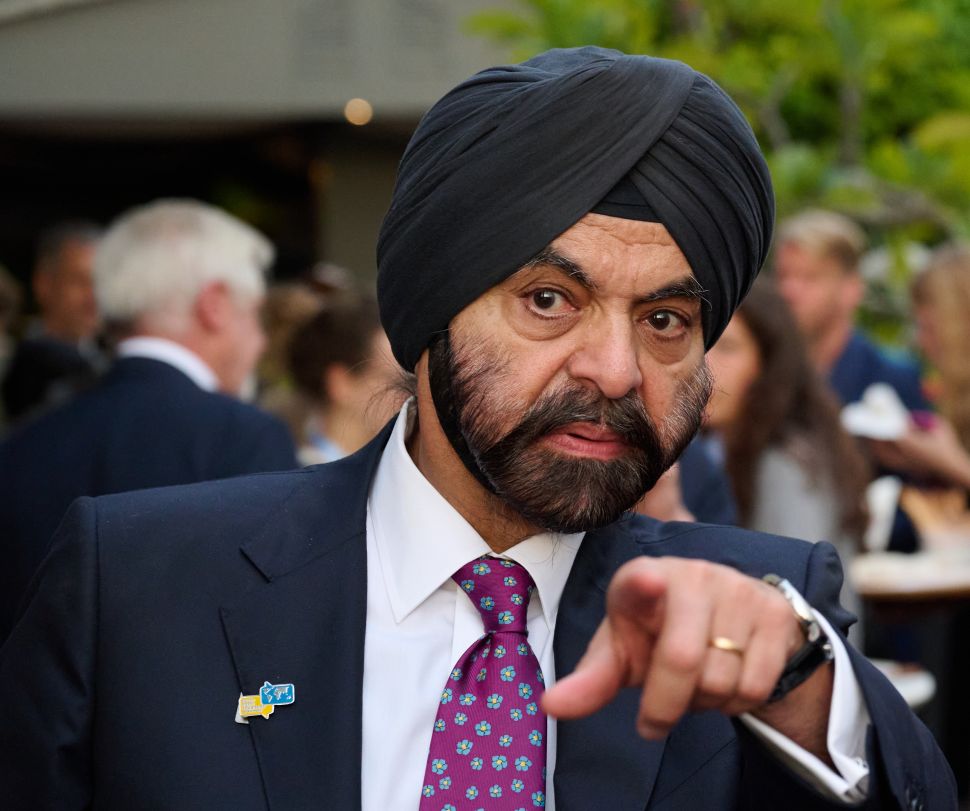
Ajay Banga (2026) ” width=”970″ height=”811″ data-caption=’World Bank President Ajay Banga gestures during an Oct. 16 reception in Bangkok marking the founding of the North-South Commission. At that week’s IMF–World Bank annual meetings, Banga emphasized the need to turn record private investment into jobs across developing economies. <span class=”lazyload media-credit”>dpa/picture alliance via Getty I</span>’>
Ajay Banga has spent three years trying to persuade private investors to put more money into developing economies. At the World Bank Group’s annual meetings in Bangkok, Thailand, last week, he had an impressive number to show for it: $112 billion.
That’s how much private capital the organization mobilized in fiscal 2026, more than triple the $35 billion it mobilized in fiscal 2022, before the former Mastercard CEO took charge.
But the increase has been uneven. Private capital mobilization in upper-middle-income countries more than quadrupled over the same period, to $50 billion. In low-income countries, it remained at approximately $3 billion.
For Banga, the goal is creating jobs in countries where millions of young people will soon enter the workforce.
“The idea of focusing on jobs is to get away from individual causes overtaking the big picture,” Banga said during an Oct. 14 discussion on investment in emerging markets.
Over the next 10 to 15 years, approximately 1.2 billion young people in developing countries will reach working age, while their economies are projected to create roughly 400 million to 420 million jobs, according to World Bank estimates published this month.
Banga said the organization must continue investing in bridges, schools, healthcare and other essential services while also supporting businesses that can employ the people who depend on them.
Public financing and philanthropy remain important. But Banga believes private investors, including pension funds and asset managers, must supply much of the additional capital.
Bringing private investors into emerging markets
One of Banga’s most consequential changes has been to simplify the process of investing alongside the World Bank Group.
In July 2024, the organization launched a unified guarantee platform, bringing together credit guarantees, trade finance guarantees and political risk insurance. The aim is to reduce the risks that discourage banks and other investors from financing projects in developing economies.
The platform has made it easier for financial institutions to structure transactions they might otherwise avoid, according to Faheen Allibhoy, J.P. Morgan’s global head of development finance and advisory.
Allibhoy described the platform as a “game-changer” during the Bangkok discussion, explaining that guarantees backed by a highly rated institution make investments easier for commercial banks to structure.
The World Bank Group issued $25 billion in guarantees during fiscal 2026, exceeding its previous goal of issuing $20 billion annually by 2030.
In South Africa, the organization is supporting a credit guarantee initiative designed to attract private investment into electricity, water, transportation and other infrastructure.
The broader program is expected to mobilize approximately $10 billion over the next decade and generate nearly 1 million direct and indirect jobs, according to World Bank projections.
Those investments and jobs have not yet materialized.
Banga is also pursuing changes to the way development banks finance projects.
In his Oct. 16 plenary remarks, he said six multilateral development banks are developing common methods for evaluating, documenting and packaging investments.
The idea is to make it easier for pension funds, insurers and other institutions to purchase or hold developing-country investments, freeing up money on development-bank balance sheets for additional projects.
The initiative remains in development. Banga has not said how much new investment it could generate.
Small A.I. and the jobs challenge
Banga also sees technology as a way to help businesses grow and become more productive.
At an Oct. 12 panel on small A.I., he described applications that could help farmers, healthcare workers and teachers without requiring expensive computing infrastructure.
One example involves a platform being developed with Google’s assistance to connect farmers in India and other countries with agricultural supplies, crop insurance, financing and buyers.
A farmer who cannot read could point a basic mobile phone at a diseased leaf, identify the problem and order an appropriate treatment through a cooperative.
The attraction, Banga argued, is that narrowly focused A.I. tools could improve productivity in economies where access to the largest language models remains limited.
On Oct. 20, the World Bank Group expanded that effort by launching its first comprehensive digital strategy at its Global A.I. and Digital Summit in Seoul, South Korea.
The strategy aims to improve internet connectivity, lower the cost of smartphones and data, expand digital financial services and help countries develop the skills needed to use A.I. applications.
The organization also announced an AI Infrastructure and Readiness Initiative, with knowledge partners including Nvidia and Cassava Technologies, to help governments obtain affordable computing capacity through shared infrastructure.
The initiative will initially focus on Africa and Latin America. The bank has not disclosed an investment total or an implementation timetable.
The digital access gap remains considerable. According to the World Bank, only 23 percent of people in low-income countries used the internet in 2025, compared with 94 percent in high-income countries.
Banga’s new strategy could help smaller businesses obtain financing and reach customers, but those gains will depend on affordable technology and reliable infrastructure.
The World Bank Group has made measurable progress in mobilizing private capital. Getting that money into poorer economies, where businesses struggle to attract financing and the need for jobs is greatest, remains unfinished work.